Down payment assistance: how it works and who qualifies
Not enough saved for a down payment? You may not need as much as you think. Thousands of programs help buyers with the down payment and closing costs. Here is how they work, and how to find yours.
The three kinds of help
Grants
Money you do not pay back. Often a percentage of the price or a set dollar amount, and usually tied to income limits.
Forgivable loans
A second loan that is forgiven after you live in the home for a set number of years. Sell or refinance early and you may owe some back.
Deferred loans
A second loan with no monthly payment. You pay it back when you sell, refinance or pay off your mortgage.
Common rules for down payment programs
Every program is different. These are the rules you will see most.
Most programs are run by state and local housing finance agencies, cities and counties. Many are open to repeat buyers too, not only first-timers.
-
First-time buyer. Often means you have not owned a home in the last three years.
-
Income limit. Your household income is under a cap for your county.
-
Primary home. You will live in the home, not rent it out.
-
Credit score minimum. Set by the program and the loan.
-
Homebuyer class. A short education course, often online.
How to get down payment assistance
- Check what you qualify for. Use the eligibility check on this page, or ask a lender who works with local programs. HUD publishes a state-by-state list of programs, and every state has a housing finance agency that runs its own.
- Get pre-approved with a lender approved for the program you want.
- Take the homebuyer class if the program requires it.
- Shop within the program's price limit with your agent.
- Close. The assistance is paid at closing, alongside your loan.
Down payment help questions
What is down payment assistance?
Down payment assistance is money from a state, county, city or nonprofit program that helps you pay your down payment or closing costs. It comes as a grant, a forgivable loan or a deferred loan.
Do I have to be a first-time buyer to get down payment assistance?
Many programs define a first-time buyer as someone who has not owned a home in the last three years, and some programs are open to repeat buyers too.
Do I have to pay down payment assistance back?
Grants usually do not need to be repaid. Forgivable loans are forgiven after you live in the home for a set time. Deferred loans are repaid when you sell, refinance or pay off the mortgage.
Can I use down payment assistance with an FHA loan?
Many programs can be combined with FHA, VA, USDA or conventional loans. The lender must be approved for the program.
How do I find down payment assistance near me?
Start with your state housing finance agency, then your city and county housing offices. A lender that works with local programs can check which ones you qualify for.
Benefits of Down Payment Assistance Programs
You may be able to qualify for a home loan with little - or even no - money down. Pairing that with down payment assistance can help you:
✅ Lower monthly payments
✅ Increase your home-buying budget
✅ Start building equity sooner
✅ Purchase a home sooner
Lower your mortgage costs
Cost of $300,000 home with a 30-year mortgage at 6% APR
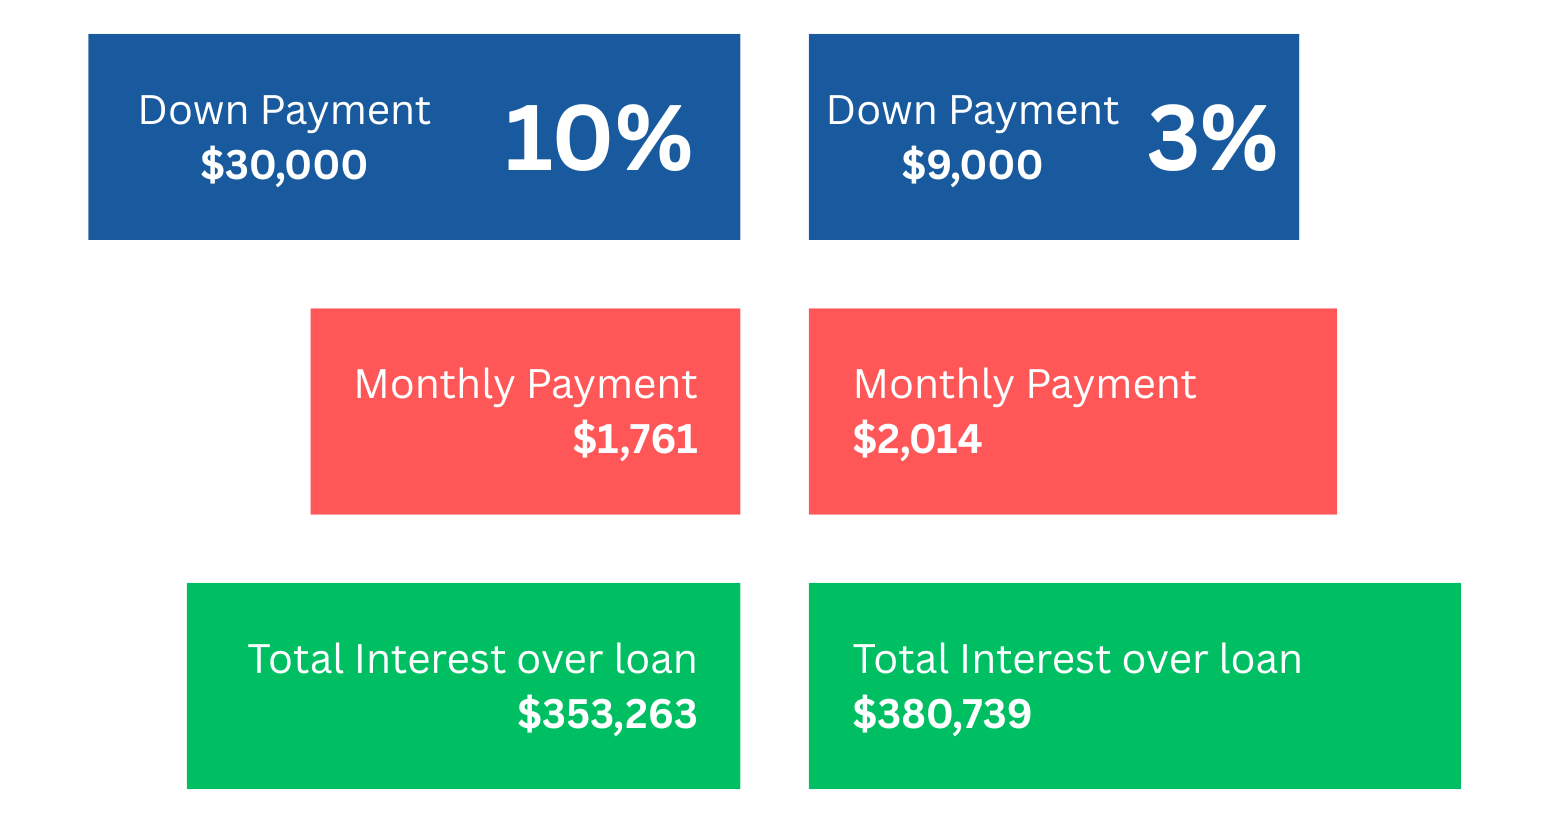
* Sample payment shown for illustration only. Actual rates and payments vary based on your loan terms, taxes, and insurance.
See if you're eligibleSteps to qualify for down payment assistance
1. Provide Qualification Information
With our easy questionnaire, see if you qualify for down payment assistance.
2. Explore DPA programs
We'll help you find the information to choose the program that works for you.
3. Talk to your lender
Discuss the programs you're interested in and verify whether they offer them.

4. Complete requirements
Reqiurements vary by program, but many ask you to complete a homebuyer education course.
How to qualify for down payment assistance
Program availability varies by area, and several eligibility factors are considered:
Household income
Household size
Employment
Home ownership history